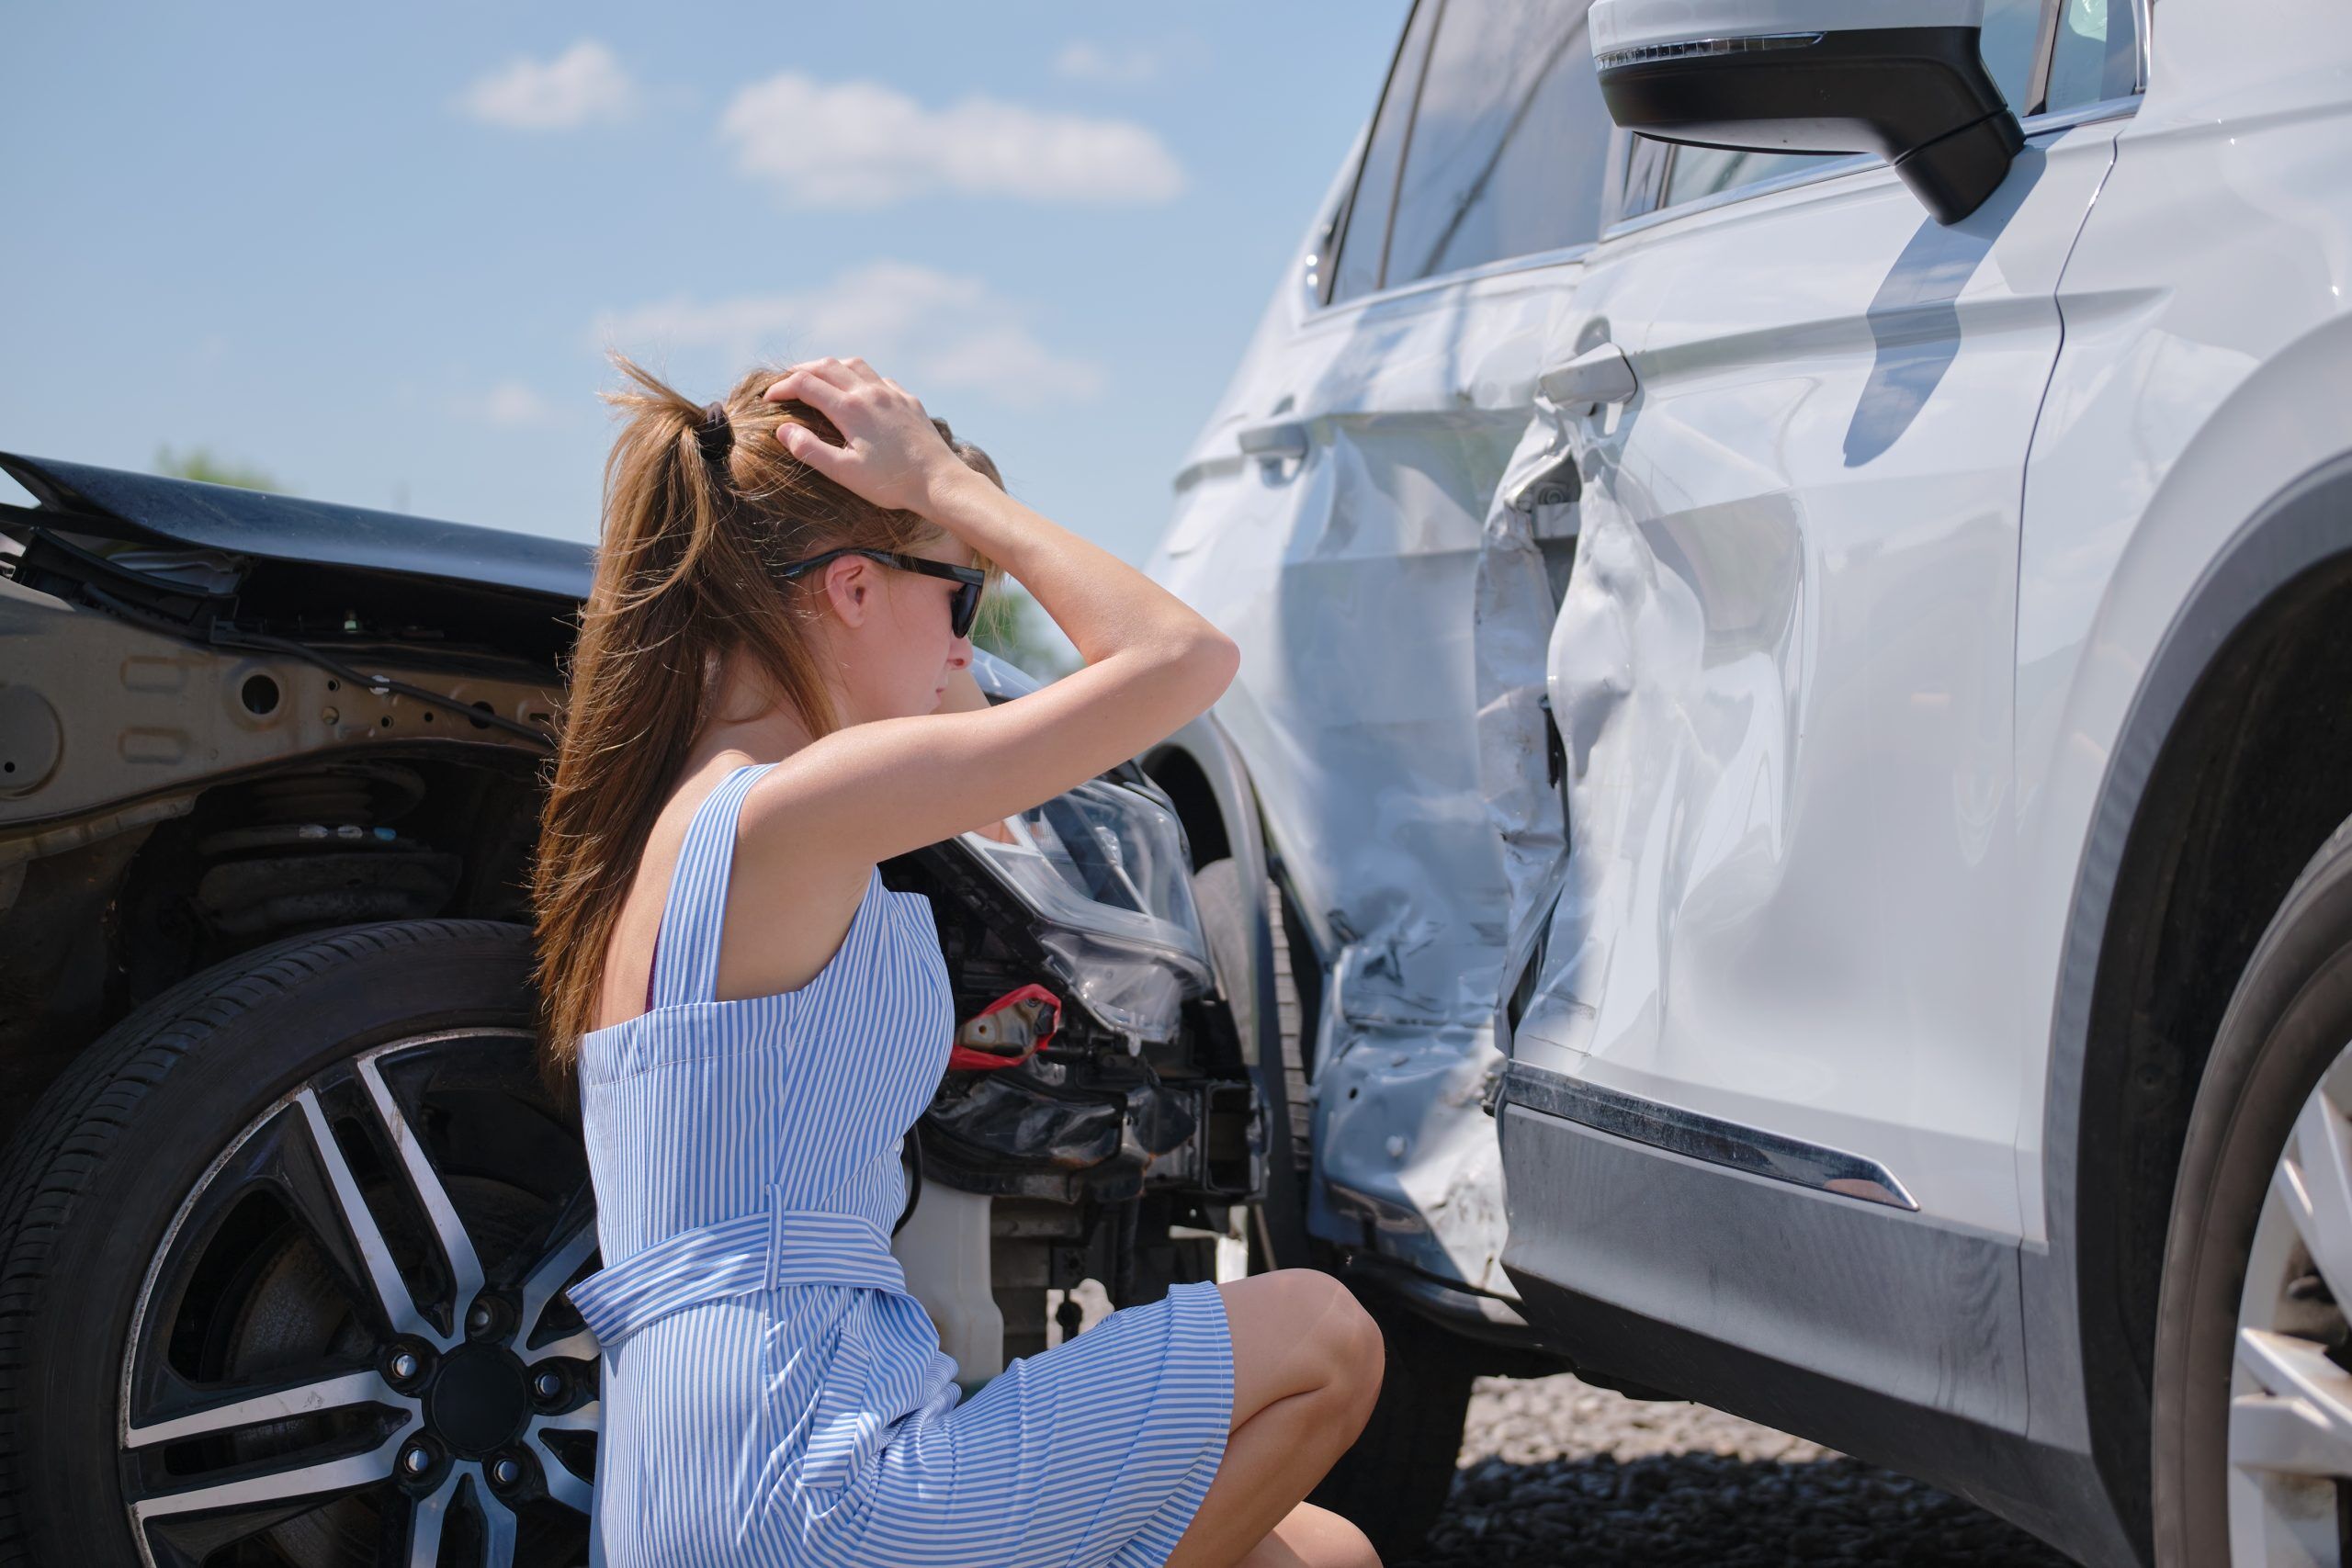
Car accidents are the case type we know best — and win most. Insurance companies know our name, and it changes how they negotiate.

Every car accident is different, but insurance companies tend to run the same playbook to minimize what they pay. Knowing how your case is likely to unfold — and what's already working against you — puts you back in control before you ever talk to an adjuster.
Our client was driving north on the highway when another driver clipped a vehicle, lost control, and struck him head-on. We secured a $750,000 settlement on his behalf.
Case results depend on the specific facts of each case. Prior results do not guarantee a similar outcome.
What you do in the first hours and days can shape what your case is worth. Here's what actually matters.
Even if you feel fine, some injuries — whiplash, concussions, internal bleeding — don't show symptoms right away. A medical record close to the accident date also becomes evidence for your claim.
A police report creates an official record of what happened and often notes an initial determination of fault — something that's hard for an insurance company to argue around later.
Photos of both vehicles, the accident scene, and any visible injuries. Get names and phone numbers for witnesses before they leave — they're much harder to track down after the fact.
Insurance adjusters often ask for a recorded statement within days, before you know the full extent of your injuries. You're not obligated to give one, and an early statement can be used against you later.
Once you accept a settlement, you can't go back for more — even if your injuries turn out to be worse than they first seemed. A free case review costs nothing and locks in nothing.
A car accident can cost more than the medical bills alone. Arizona law lets you pursue compensation for the full impact — not just whatever the insurance company offers first.
Hospital bills, surgeries, medications, physical therapy, and long-term care.
Income lost while you recover, plus future earning capacity if the injury changes what you can do.
Compensation for the physical pain and emotional toll the accident caused, not just the bills.
Vehicle repair or replacement, plus anything else damaged in the accident.
In cases of gross negligence — like drunk driving — additional damages meant to punish the at-fault party.
Two rules shape almost every car accident claim in Arizona: how long you have to file, and what happens if fault isn't 100% clear-cut. Both usually work in your favor more than people assume.
Arizona lets you recover damages even if you were partially at fault — your compensation is reduced by your percentage of fault, not eliminated. Don't assume you have no case just because fault isn't 100% clear-cut.
In some cases, you may have as little as 6 months to file your complaint, and certain claims must settle within about a year. Start the process now instead of waiting and potentially missing out.
A real method, not a script. Built around never settling just to close your case.
Free case review — we hear what actually happened, no pressure, no obligation.
We build the evidence — police reports, medical records, fault documentation — before insurance can spin the story.
We negotiate for full value. If the insurance company won't move, we don't settle just to close your case.
You get paid, and you're never left wondering what happens next — we walk you through every step.
No actors. No scripts. Just clients.
Arizona's statute of limitations for car accident claims is two years from the date of the accident. Waiting too long can mean losing your right to recover anything, so it's worth a free case review as soon as you're able.
Arizona follows comparative negligence rules, meaning you can still recover damages even if you were partially at fault — your compensation is reduced by your percentage of fault, not eliminated.
It depends on your medical costs, lost wages, and how clearly fault can be proven. We give you a real, honest number after reviewing your case — not a guess to get you off the phone.
You're not required to have one, but insurance adjusters negotiate against unrepresented people differently. There's no cost to find out where you stand — the free case review carries zero obligation.
Arizona requires drivers to carry insurance, but not everyone does. If you have uninsured or underinsured motorist coverage, we can often pursue a claim through your own policy instead.
Free case review. $0 upfront cost. Real people answer, day or night.
No fee unless we recover for you — the free case review carries zero obligation.